

Note: All market prices and spot figures are as of 9 September 2026. The FOMC decision lands on 16 September, so these numbers will move.
1. The hike crossed 50 percent
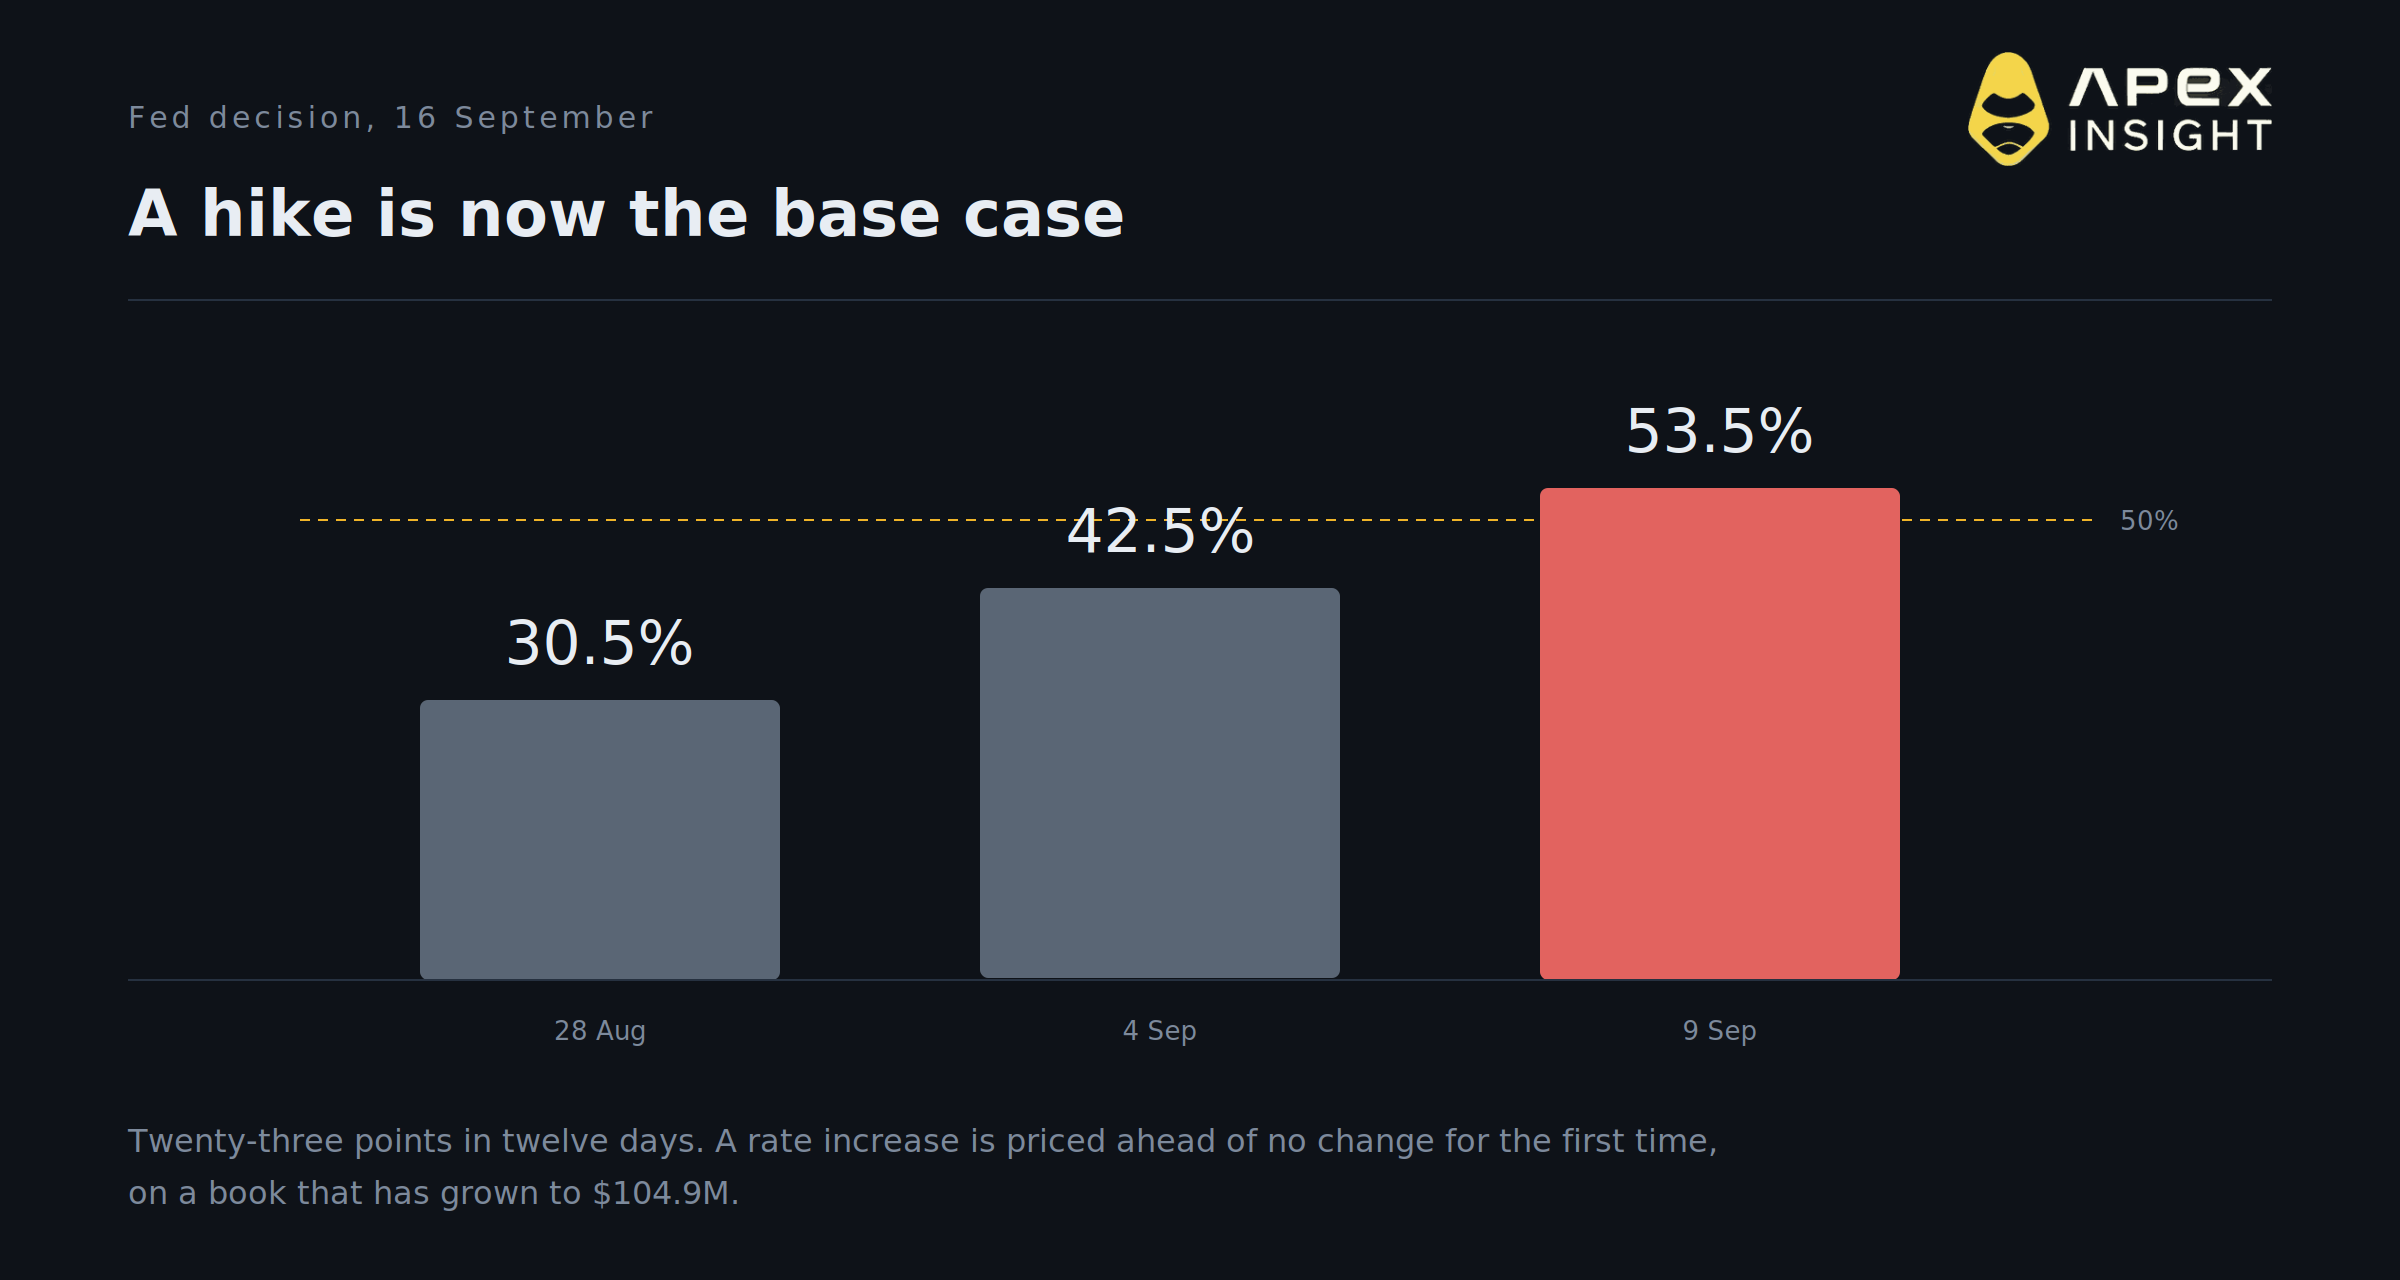
On 28 August the contract priced at 30.5 percent. On 4 September, 42.5 percent. Today, 53.5 percent.
Twenty-three points in twelve days, and it has now passed the level where a market stops describing a risk and starts describing an expectation.
The current target range is 3.50 to 3.75 percent. The board's central case is that it goes up.
2. A cut has effectively disappeared
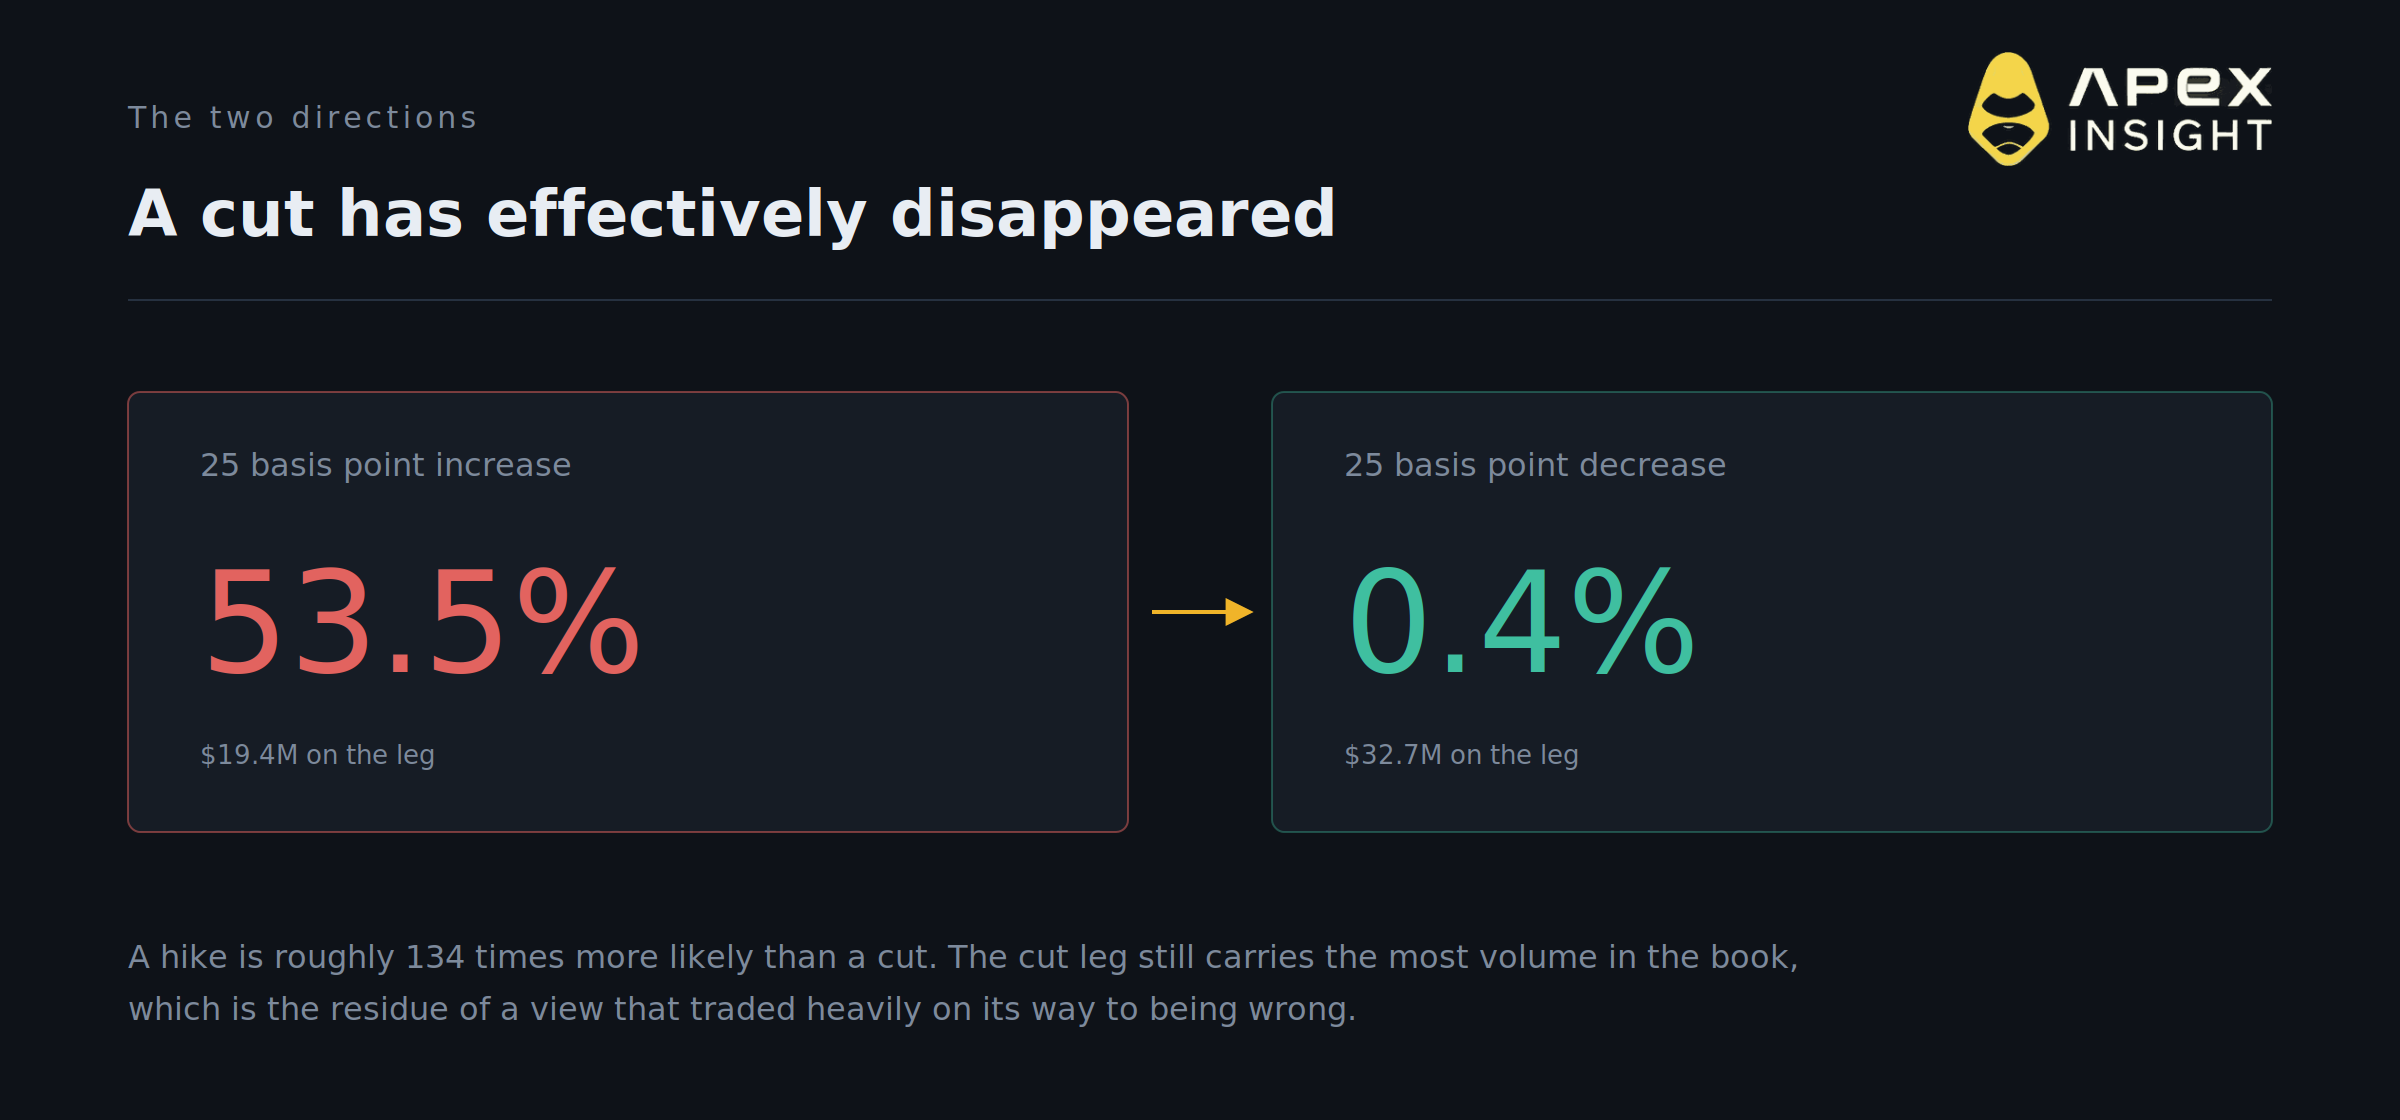
The 25 basis point decrease leg prices at 0.4 percent. A 50 basis point cut prices at 0.1 percent.
An increase is roughly 134 times more likely than a decrease.
For most of the past two years the only live question about this committee was when easing would start. It is now whether tightening resumes this month.
3. Most of the money is on outcomes that cannot happen
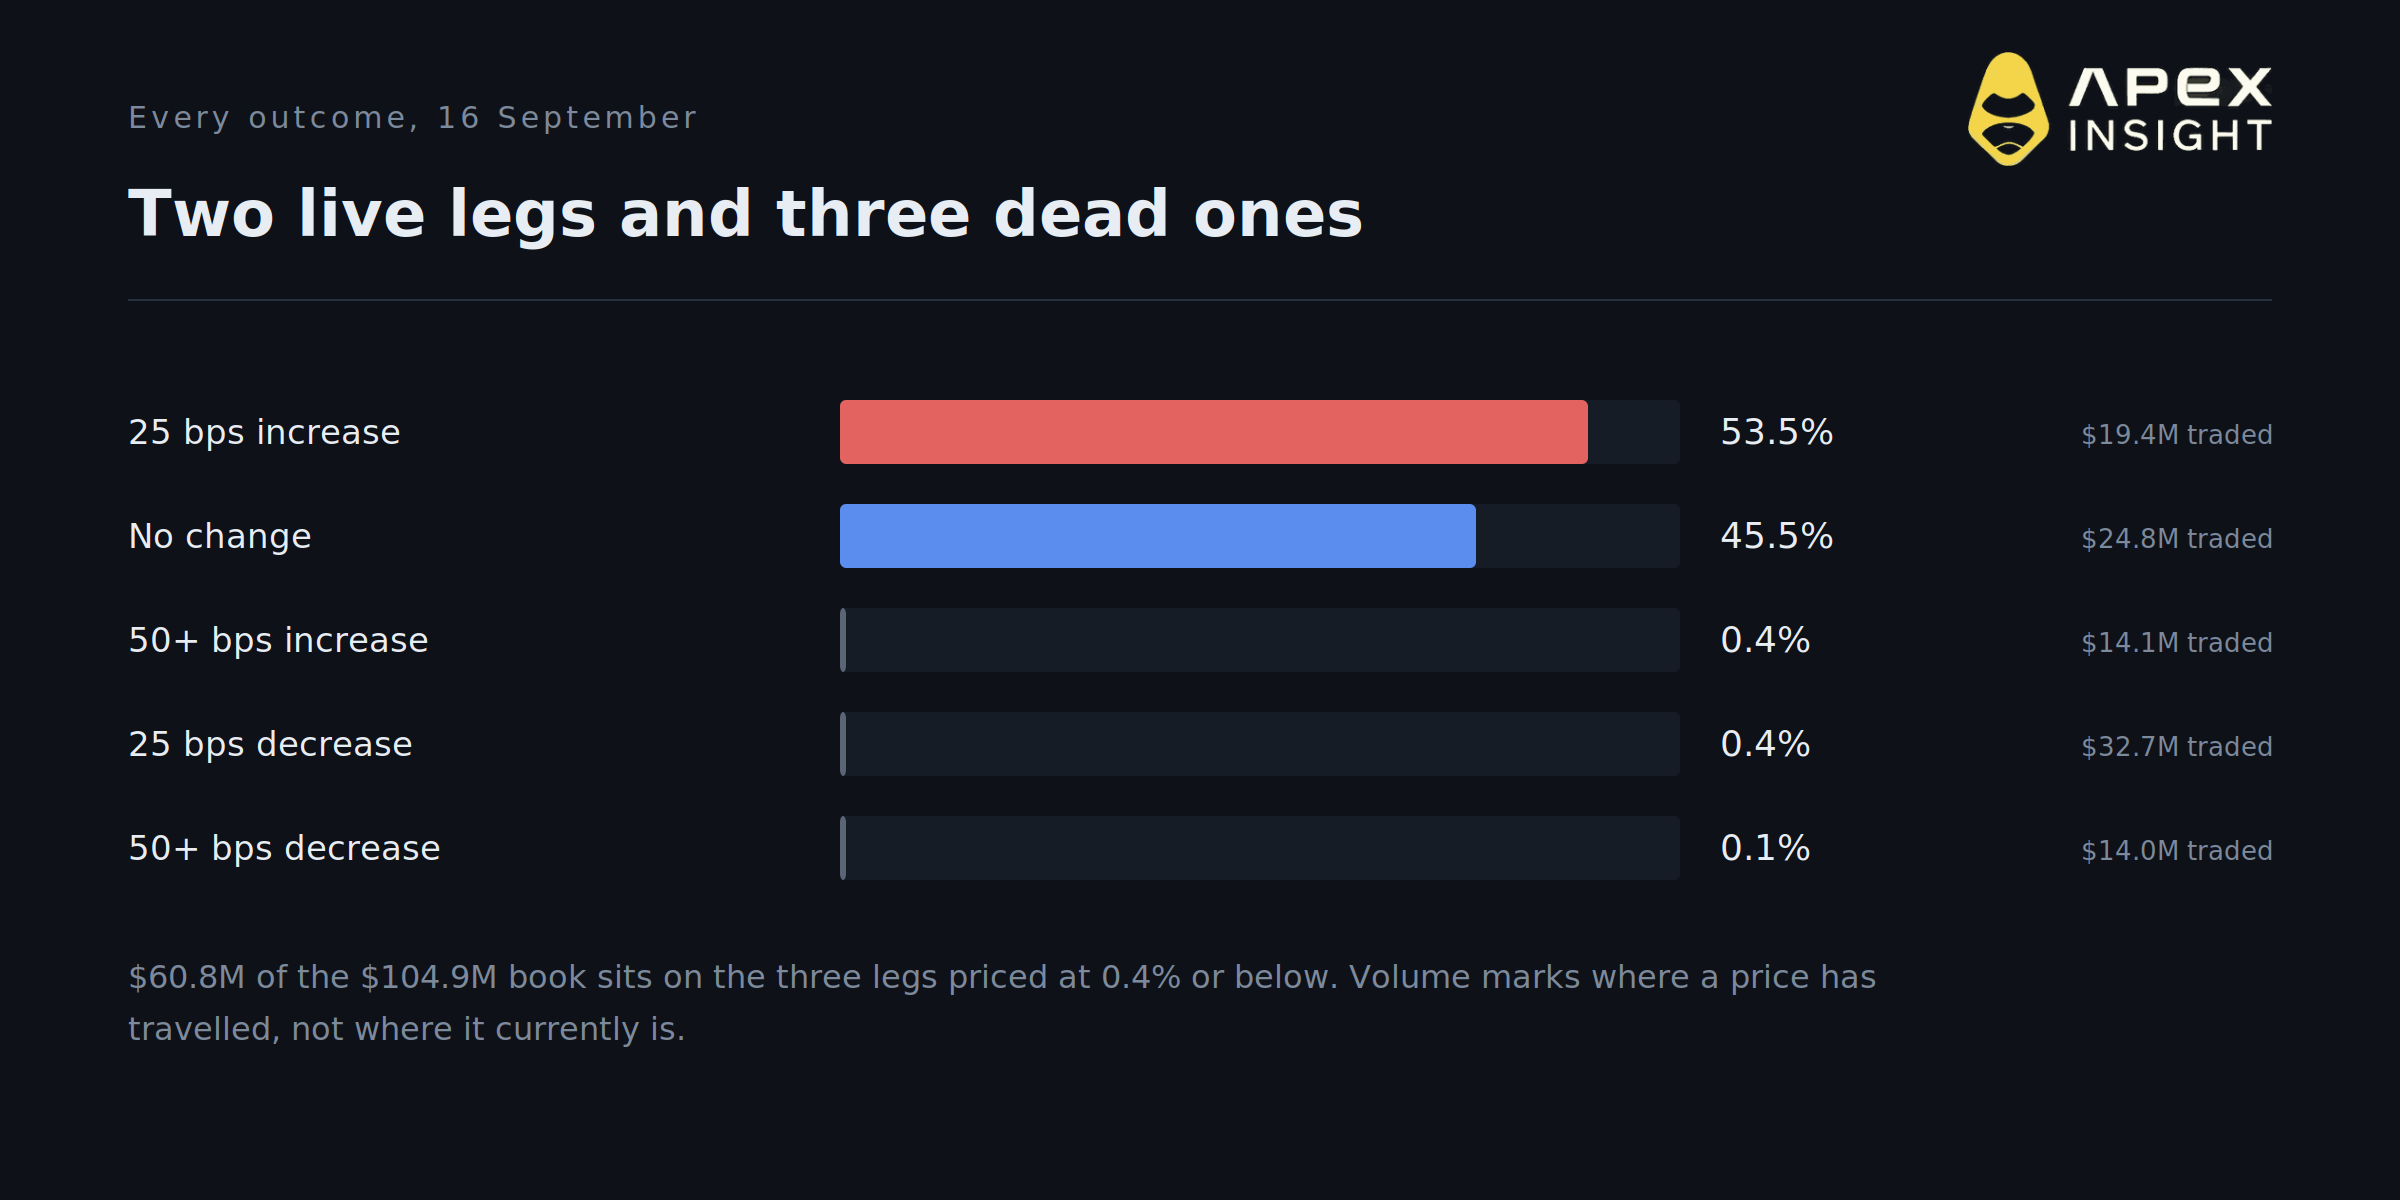
Here is the detail worth taking from the book rather than the headline. The 25 basis point decrease leg carries $32.7M, more volume than any other outcome, and prices at 0.4 percent. The 50 basis point cut carries $14.0M at 0.1 percent, and the 50 basis point hike $14.1M at 0.4 percent.
Together, $60.8M of the $104.9M book sits on legs priced at or below 0.4 percent.
Those are not live positions. They are the accumulated record of a view that traded heavily on its way to being wrong. Volume marks where a price has travelled, not where it currently is, and anyone sizing conviction by book depth here would reach exactly the wrong conclusion.
4. Three things moved it
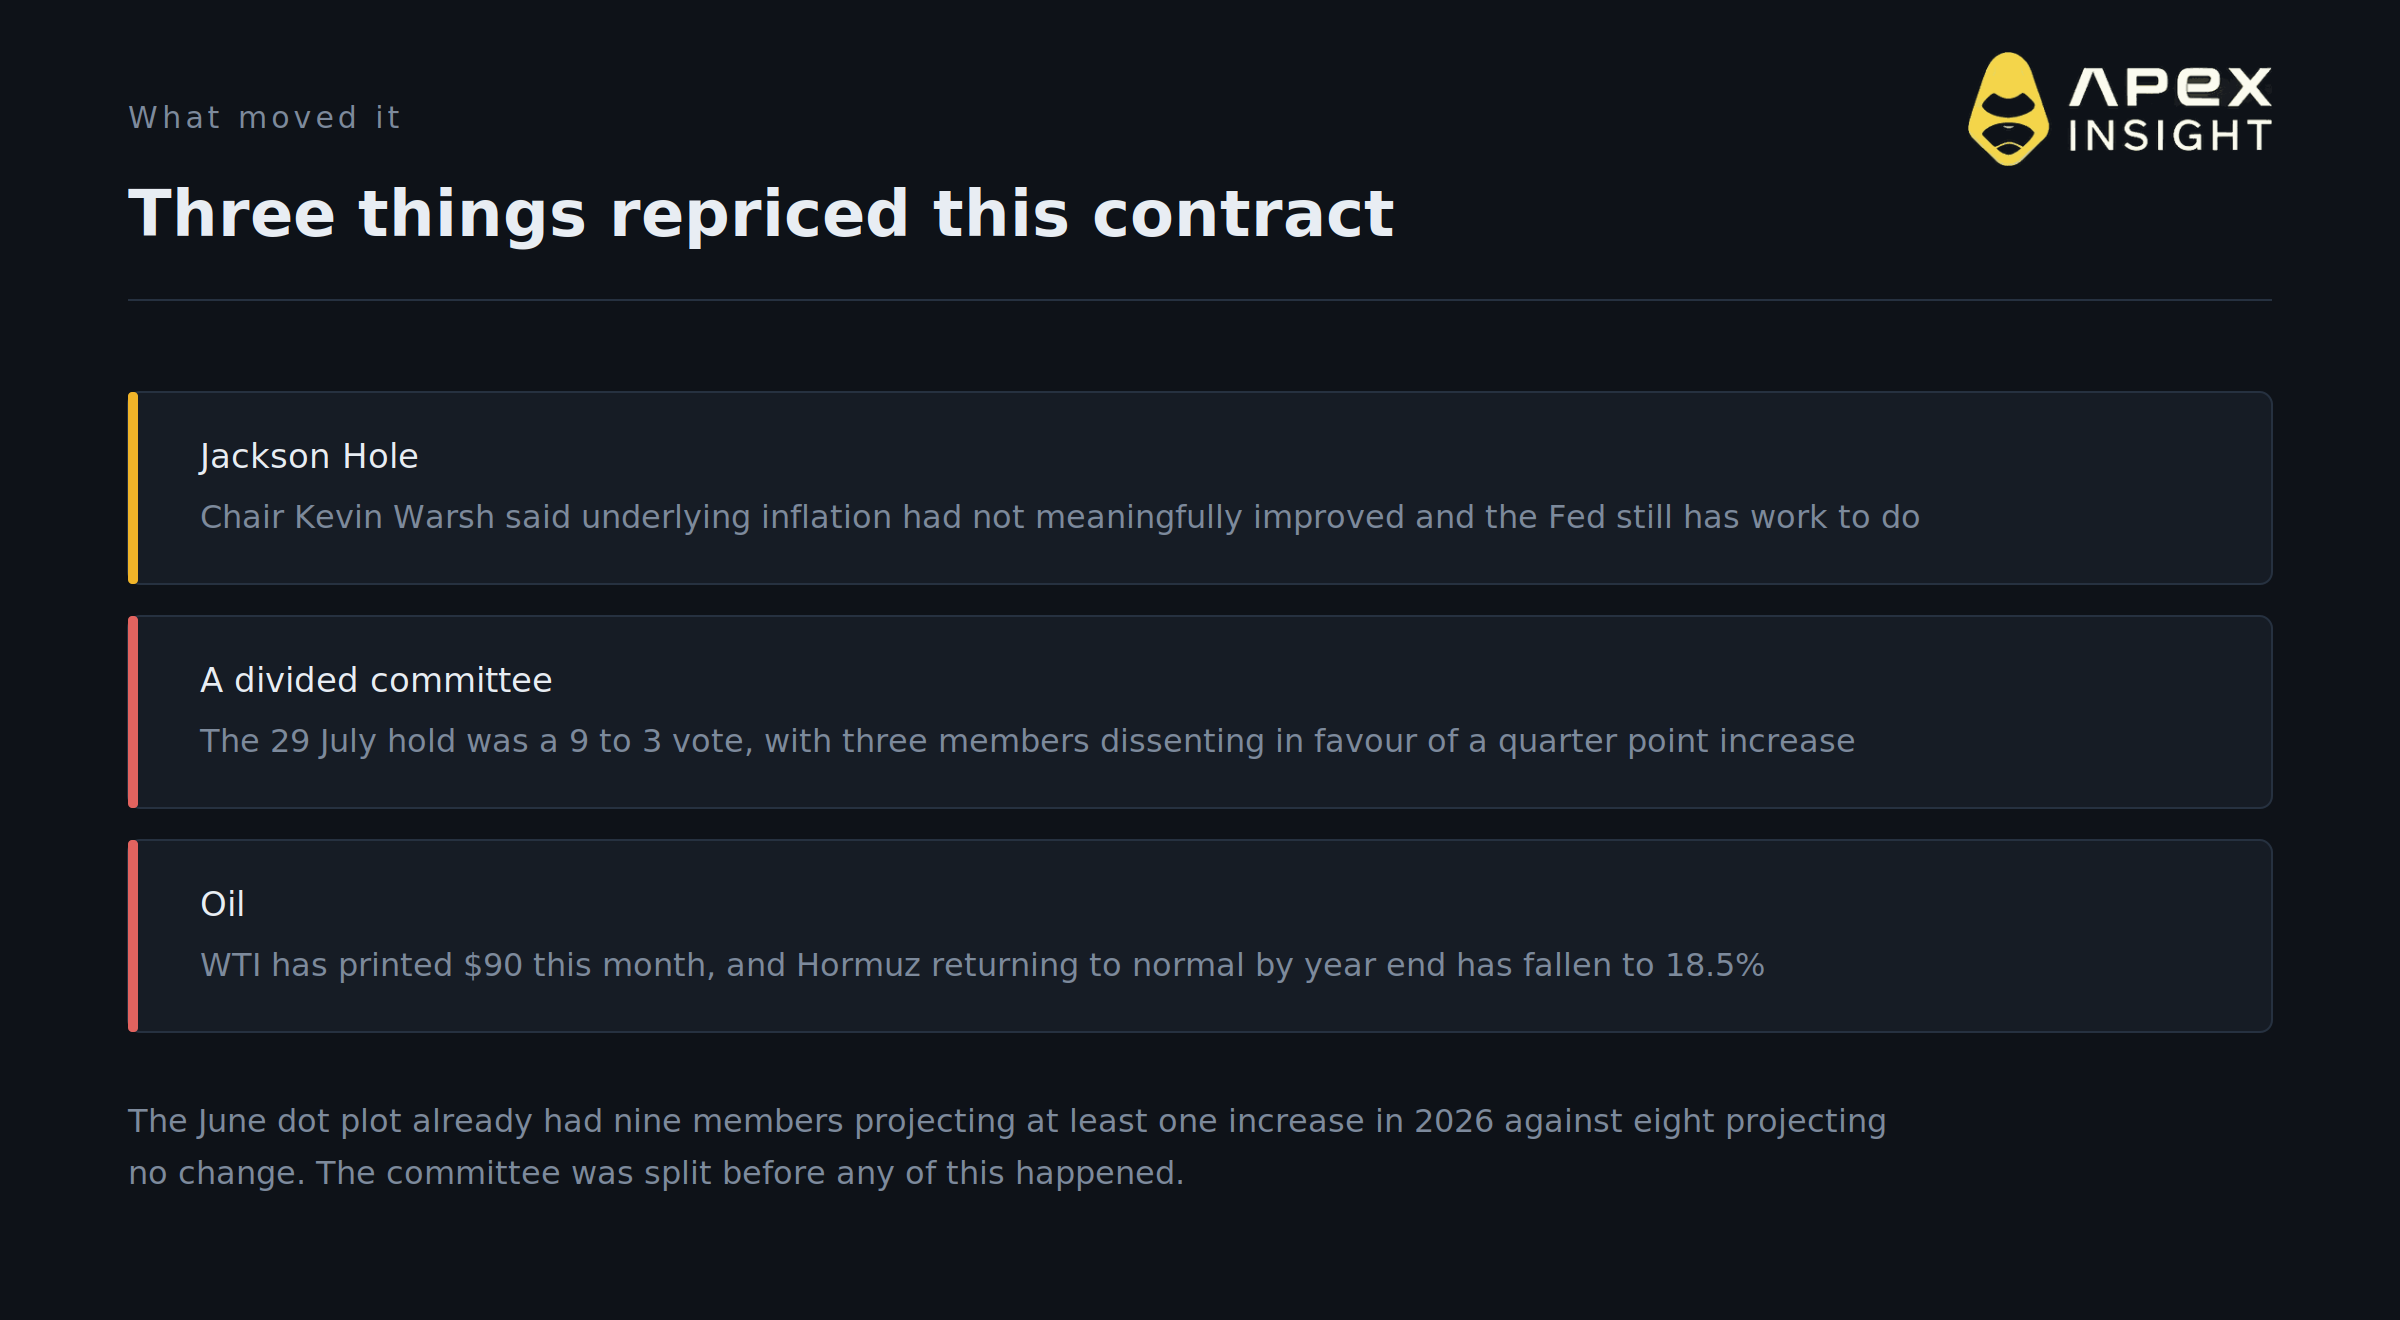
At Jackson Hole, Chair Kevin Warsh said underlying inflation trends had not meaningfully improved and that the Fed still has work to do. The contract has gained twelve points since.
The committee was already split. The 29 July decision to hold was a 9 to 3 vote, with three members dissenting in favour of a quarter point increase, and the June dot plot had nine members projecting at least one hike in 2026 against eight projecting none.
Underneath both sits oil. WTI has already printed $90 this month, and the market on Strait of Hormuz traffic returning to normal by year end has fallen to 18.5 percent on a $10.7M book. Supply pressure that does not resolve is inflation pressure that does not resolve.
5. Crypto went the other way
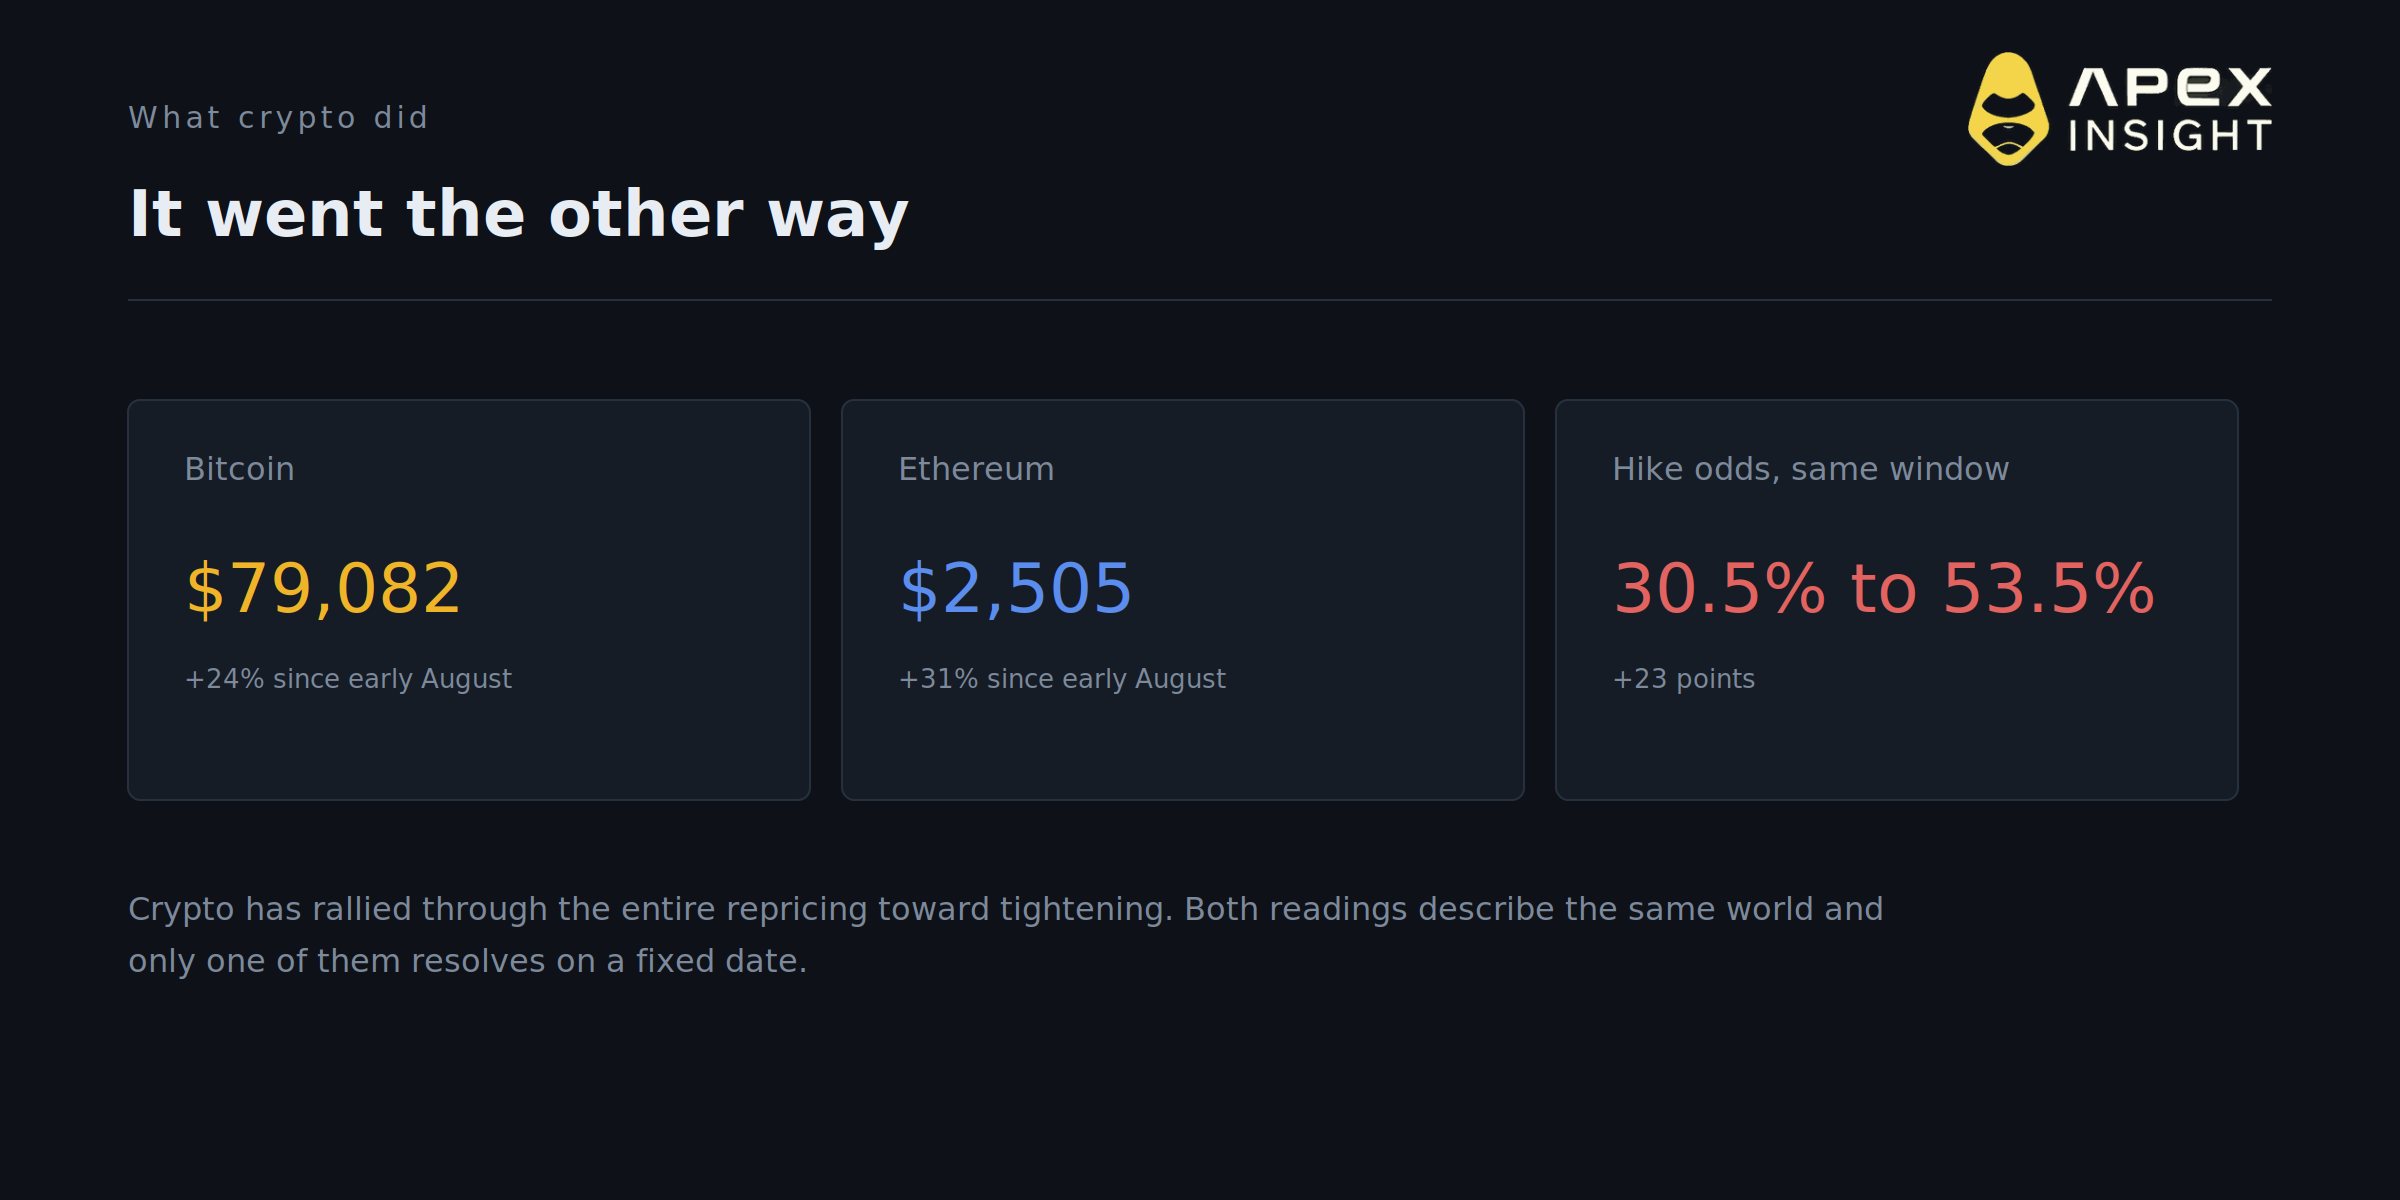
Bitcoin trades at $79,082, up roughly 24 percent since early August. Ethereum is at $2,505, up around 31 percent.
Over that same window the hike contract gained 23 points.
Both of those are readings of the same world, and only one of them resolves on a fixed date. There is a version where they are compatible, since a fully anticipated hike can pass without incident and a Fed seen as credible on inflation reduces tail risk rather than adding it. But that is a specific argument, and it is not the one most of the market is making out loud.
Four months in one chart
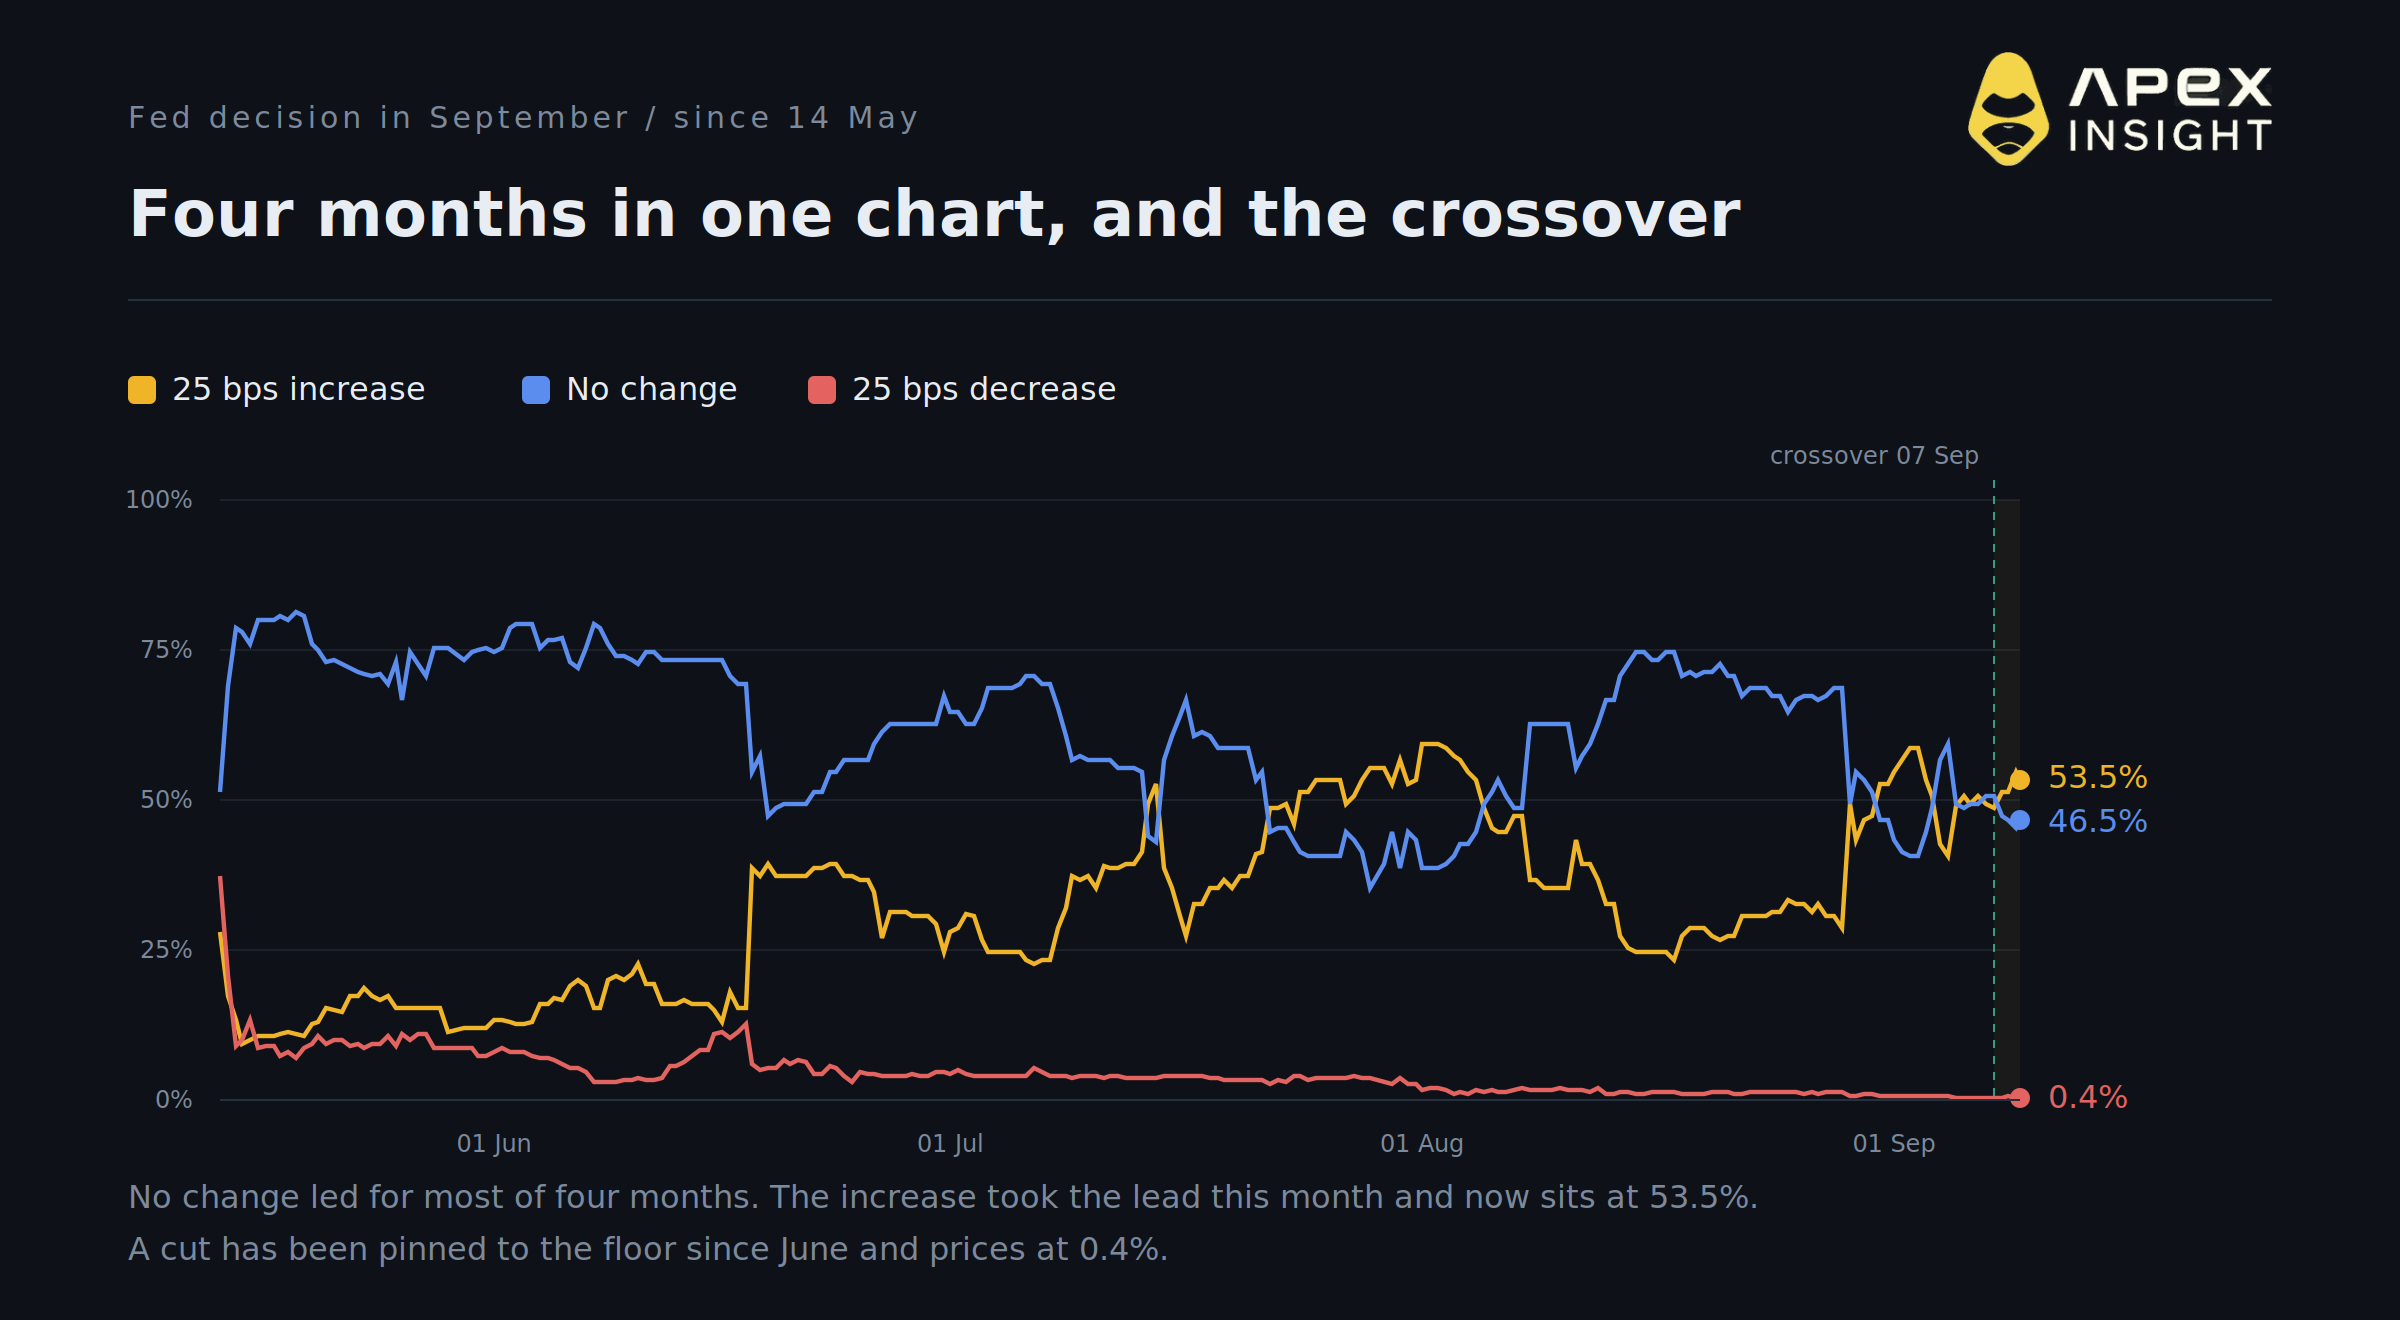
This is the whole contract since it opened on 14 May.
No change led for almost the entire period, holding above 70 percent through late May and again in mid-August. The increase spent June and July in the twenties and thirties. The two lines converged repeatedly through late August and crossed for the last time on 7 September, the day Stage 1 opened.
The cut, in red, is the flat line along the bottom. It started near 40 percent in May, fell below 10 percent within days, and has been pinned to the floor since June.
Read across the whole series and the pattern is clear: this contract has been volatile all summer, has changed leadership several times, and has never before settled with the increase on top.
Where this goes
The decision lands on 16 September, three days after Stage 1 of the campaign closes. Between now and then the number to watch is not a US data release, it is the Hormuz contract, because oil has been the upstream variable moving Fed pricing all year.
Tomorrow this series looks at the other half of the story: the rate cut trade that has been quietly abandoned, and the $44M still sitting on it.
Trade it
Political Markets Season is live on ApeX Omni. Four stages, four political markets, a 6,000 USDT prize pool. Stage 1 is the Fed Decision in September, running to 13 September 00:00 UTC.
Spot prediction trading on Polymarket order books. No leverage, no liquidation, no KYC. Trade the odds, not the outcome.
We appreciate your continued support.
Published by ApeX. For informational and educational purposes only. Not investment advice, and not a forecast or endorsement of any political or policy outcome. Trading involves risk, including total loss.